
FIFO vs Weighted Average in Pakistan: Which Stock Valuation Method Should Your Business Use?
In short: FIFO treats your oldest stock as sold first. Weighted average uses one blended cost for all units. When prices are rising, FIFO shows higher profit and a higher closing stock value, while weighted average gives steadier margins. FIFO usually suits medicine, food and other dated goods. Weighted average usually suits hardware, spare parts, chemicals and other stock that gets mixed together. Whichever you choose, use it consistently, because a change for tax purposes needs the Commissioner’s written permission.
Why your stock valuation method changes your profit
Gross profit is sales minus the cost of the goods you sold. When the same item is bought at different prices during the month, someone has to decide which price belongs to the goods sold and which belongs to the goods still in the godown. That decision is your stock valuation method.
In Pakistan this matters more than textbooks suggest. Dollar movements, freight and supplier price changes can move your purchase price several times in one season. The method you use then changes your reported profit, your closing stock on the balance sheet, the taxable income you start from and the margins you use to set selling prices.
A worked example: same stock, different profit
Take a trader of cooking oil cartons in October. The amounts below are examples only.
| Date | Transaction | Cartons | Rate (Rs) | Amount (Rs) |
|---|---|---|---|---|
| 1 Oct | Opening stock | 100 | 5,000 | 500,000 |
| 10 Oct | Purchase | 100 | 5,400 | 540,000 |
| 20 Oct | Purchase | 100 | 5,800 | 580,000 |
| Total available | 300 | 1,620,000 | ||
| 25 Oct | Sale | 180 | 6,500 | 1,170,000 |
That leaves 120 cartons in the godown. This is how each method values the month:
| Item | FIFO (Rs) | Weighted average (Rs) |
|---|---|---|
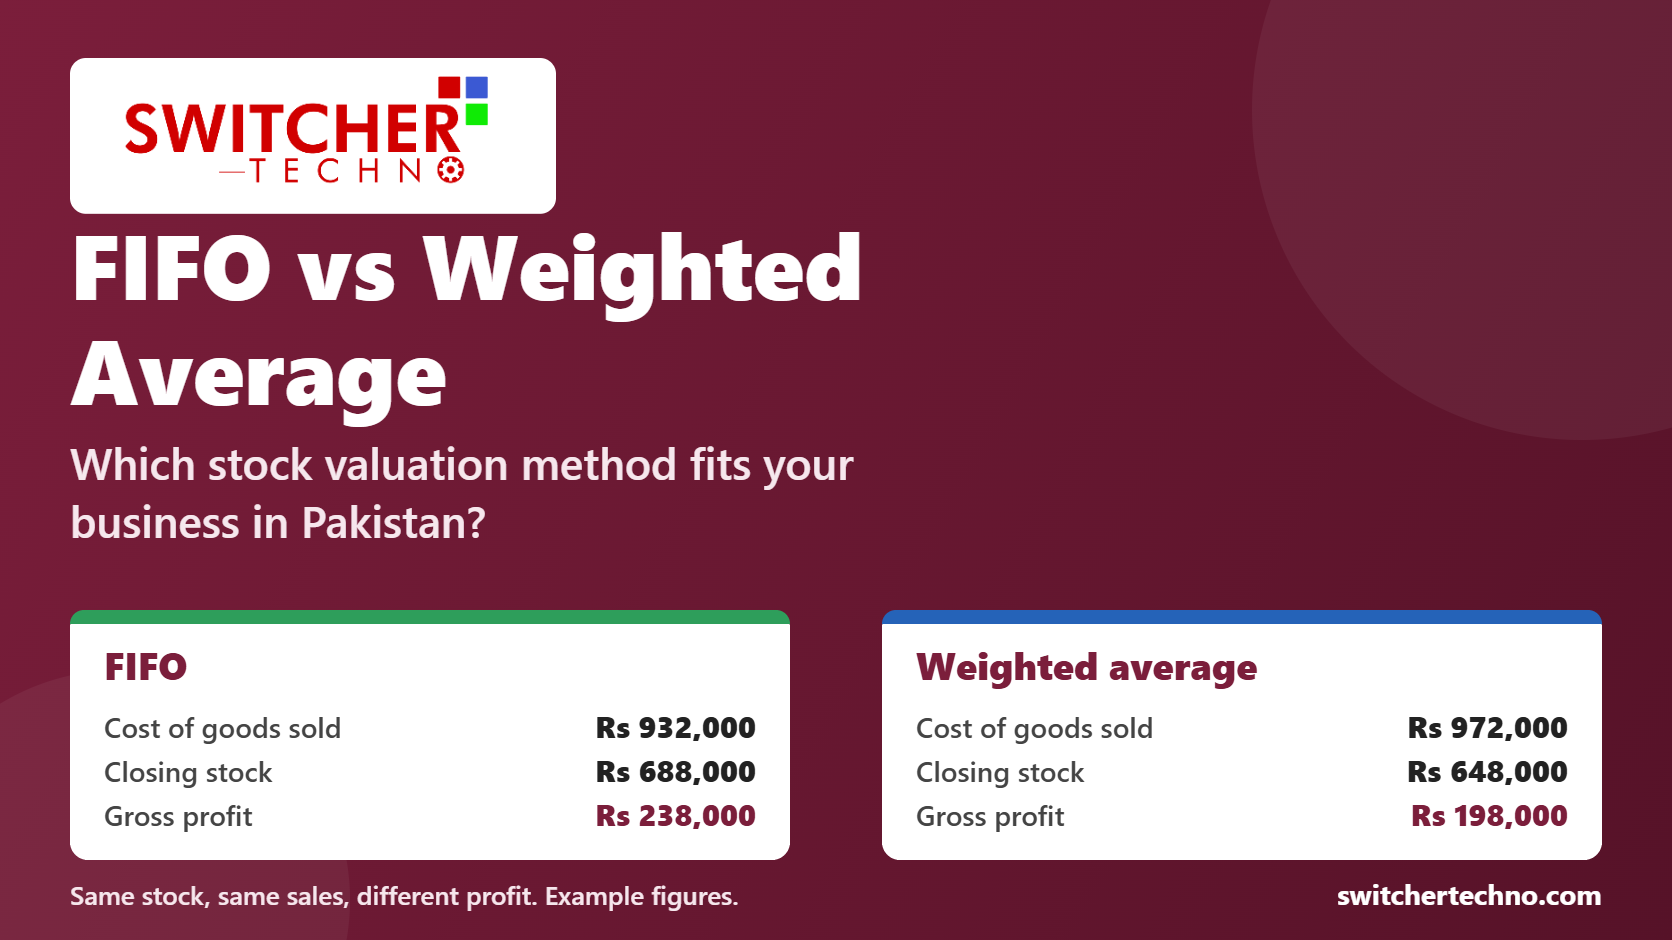
| Cost of the 180 cartons sold | 100 × 5,000 + 80 × 5,400 = 932,000 | 180 × 5,400 = 972,000 |
| Closing stock of 120 cartons | 20 × 5,400 + 100 × 5,800 = 688,000 | 120 × 5,400 = 648,000 |
| Gross profit on sales of 1,170,000 | 238,000 | 198,000 |
The weighted average rate is Rs 1,620,000 ÷ 300 = Rs 5,400 per carton. FIFO shows Rs 40,000 more profit this month, and that same Rs 40,000 sits in its higher closing stock. No extra money has come in. It is a timing difference that reverses when the remaining stock is sold.
If prices were falling, the result would flip: FIFO would show the lower profit.
The example above uses one average for the whole month. Most inventory software instead recalculates the average after every purchase, which is called moving average. If the trader had sold 50 cartons on 15 October and 130 on 25 October, the 15 October sale would be costed at Rs 5,200 and the later one at Rs 5,440. Total cost would be Rs 967,200 rather than Rs 972,000. Ask your software vendor which version it uses.
FIFO vs weighted average at a glance
| Point | FIFO | Weighted average |
|---|---|---|
| Logic | Oldest stock is treated as sold first | All units carry one blended cost |
| Profit when prices rise | Higher | Lower and steadier |
| Closing stock when prices rise | Closer to current prices | Lower |
| Record keeping | You must track each purchase layer | Simpler, with one rate per item |
| Margin reports | Can jump as cheap layers run out | Smoother from month to month |
| Best for | Dated goods and stock that moves in clear lots | Mixed, bulk or interchangeable stock |
Which method fits your type of business?
These are common starting points, not rules. Your auditor or tax adviser should confirm the final choice.
| Business | Usual fit | Why |
|---|---|---|
| Pharmacy and medicine distribution | FIFO | Older batches should physically leave first. See our guide for pharmacies and medical distributors. |
| Food, FMCG and cosmetics | FIFO | Shelf life drives the way stock moves |
| Hardware, spare parts and building material | Weighted average | Same items from many purchases sit together in one bin |
| Chemicals, oil, yarn and other bulk stock | Weighted average | Separate lots get physically mixed |
| Wholesale and distribution | Either | Depends on the product. Read our wholesale and distribution guide for reports to demand. |
| Mobile phones, vehicles and other serial-numbered goods | Actual cost of each item | Each unit can be identified, so IAS 2 expects specific identification where items are not interchangeable |
FEFO is not a valuation method. First-expiry-first-out tells your godown which batch to pick. You can pick by expiry and still value stock on FIFO or weighted average, but your records must keep batch and expiry details. For pharmacies, our guide to medicine batch and expiry tracking shows how to run FEFO day to day.
What the rules say in Pakistan
- Income tax: Section 35 of the Income Tax Ordinance, 2001 deals with stock-in-trade. Closing stock is taken at the lower of cost and net realisable value. Cost can be worked out on first-in-first-out or average cost, and changing the method needs the Commissioner’s written permission.
- Cost basis for tax: Businesses on the accrual basis use absorption cost. Cash-basis businesses can choose prime cost or absorption cost.
- Financial reporting: IAS 2 allows FIFO and weighted average, and prohibits LIFO. Similar inventory should use the same formula across the business.
- Physical stock count: step-by-step procedure
Do not forget the lower of cost and market test
A method only gives you cost. You must still compare it with net realisable value, meaning the expected selling price less the costs still needed to sell the item. Suppose those 120 cartons cost Rs 5,400 each on weighted average, but the market falls and you can only net Rs 5,100. You write closing stock down by 120 × Rs 300 = Rs 36,000. Near-expiry, damaged and slow-moving stock are the usual cases.
Five mistakes that distort stock value
- Leaving landed cost out. Import duties, freight, and handling that brings stock to its present location belong in its cost. Booking them straight to expense understates stock and overstates this month’s costs.
- Treating adjustable sales tax as cost. Input tax you can claim back generally should not sit in the stock rate. Input tax you cannot recover usually does.
- Allowing negative stock. Selling before the purchase is entered breaks the rate calculation. Enter purchases on time, or block negative stock in the system.
- Mixing units. Buying in cartons and selling in pieces without a correct conversion quietly destroys the average rate.
- Posting back-dated entries after closing. A late purchase bill or return can change the cost of sales already reported. Close each month properly and control who can edit old dates.
How to apply your method in Excel or software
Excel can handle a small list of items, but FIFO layers across hundreds of items and several godowns quickly become unreliable. This is one of the clear signs a business has outgrown Excel. Good accounting software should post the cost of each sale automatically and link the stock balance to your ledgers.
Before you buy, ask the vendor to show you these on your own data:
- Which valuation method it uses, and whether the average is monthly or moving
- How landed cost gets added to purchases after the goods arrive
- Stock valuation by item and by godown on any past date
- Whether the stock report agrees with the inventory balance in your chart of accounts
- Whether it records batch and expiry, if you need them
Not sure your stock value is right?
Bring a few of your real items to a free demo of Switcher Techno’s accounting and inventory software. We will walk through purchases, sales and closing stock with you, with local support from Karachi and Lahore.
Frequently asked questions
What is the difference between FIFO and weighted average?
FIFO treats the oldest stock as sold first, so closing stock carries the latest purchase prices. Weighted average mixes all purchase prices into one average cost per unit and uses it for both sales and closing stock.
Which method shows higher profit in Pakistan when prices are rising?
FIFO usually shows higher profit when purchase prices are rising, because older and cheaper stock goes to cost of goods sold. Weighted average shows a lower profit in the same period. The total profit evens out over time once all the stock is sold.
Is LIFO allowed in Pakistan?
LIFO is not a practical option. IAS 2 prohibits it for financial reporting, and the Income Tax Ordinance, 2001 refers to first-in-first-out or average cost for stock-in-trade.
Can a business change from FIFO to weighted average?
Yes, but plan it carefully. For tax, a change of method needs written permission from the Commissioner. In your accounts it should only be made for a sound reason and disclosed properly, so speak to your accountant first.
Which method is better for a pharmacy or medicine distributor?
FIFO usually fits best because older batches should physically leave first. Pick by expiry date in the godown, and keep batch and expiry records whichever valuation method your accounts use.
Can I use both methods in the same business?
Different types of inventory can use different methods when their nature or use is genuinely different. Similar items should use the same method across all branches and godowns, and the choice should stay consistent from year to year.
This article is general guidance for Pakistani businesses as at November 2026. Amounts are examples only. It is not accounting or tax advice; confirm the method and tax treatment for your business with a qualified accountant or tax adviser.
